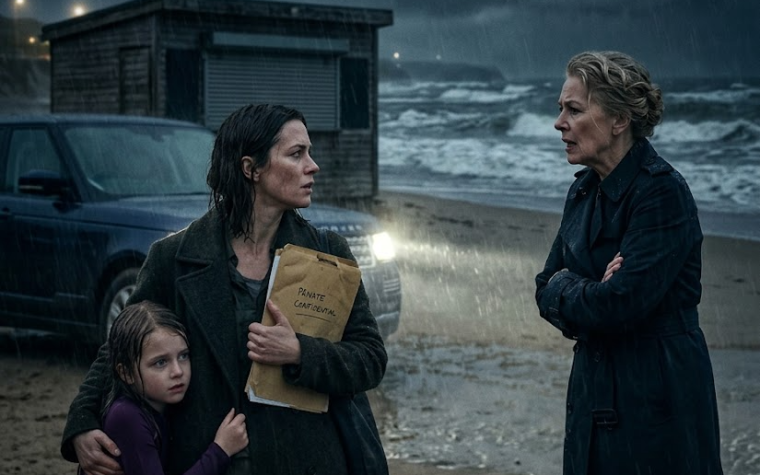
Grandpa lifted one finger before I could touch the cream envelope.
Outside my hospital room, my mother struck the locked door again.
“Open this door, Mara.
That house belongs to this family.”
Eli stirred in Nora’s arms.
His tiny face tightened, and the newborn nurse turned her body so he was shielded from the noise.
Grandpa picked up my phone from the tray, pressed the record button, and placed it beside the door.
“Let her keep talking,” he said.
Chloe’s voice rose over my mother’s.
“We already submitted the paperwork.
She can’t ruin this because she got into a stupid accident.”
The room went completely still.
Nora looked at me.
Then she reached for the call button and asked the desk to send security.
Grandpa’s expression did not change, but the hand around his silver cane tightened.
“That,” he said quietly, “is what your mother neglected to mention.”
He returned to the envelope and removed the first document.
It was the deed to the house my mother had lived in for nine years.
My name appeared under the words sole owner.
I had always known the house was legally mine.
After my father died, my mother could not qualify for a mortgage.
She had no steady income, little savings, and a credit history damaged by years of late payments.
I had bought the property so she would have somewhere secure to live.
I had made the down payment.
I had signed the loan.
I had paid every installment.
My mother still called it her house.
At first, the phrase had seemed harmless.
Over time, it became a weapon.
Any question about expenses was met with outrage that I was trying to control her in her own home.
Chloe moved into the guest room for what was supposed to be six weeks and stayed for four years.
Neither of them paid rent.
I covered the mortgage, taxes, insurance, utilities, groceries, repairs, and most of their personal emergencies.
The amount settled into a regular monthly transfer of $4,500, though there were always additional requests.
A broken appliance.
A medical bill.
A business course Chloe never finished.
A deposit for a boutique that never opened.
I had kept paying because grief had made all three of us fragile after Dad died, and because being useful was easier than admitting my mother loved what I provided more consistently than she loved me.
Grandpa placed a second document beside the deed.
It was an application for a home-equity loan.
The requested amount was $180,000.
The stated purpose was property improvement and small-business investment.
The proposed borrower was me.
I had never seen the application before.
Attached to it was a scanned owner-consent form with my signature at the bottom.
It looked almost right.
Someone had copied my name from an older insurance document, but the angle was wrong and the final stroke was too heavy.
“Where did you get this?” I asked.
“The bank called the office because your father once listed me as an emergency contact on a family trust account,” Grandpa said.
“They could not reach you, and something about the application concerned their verification officer.”
My phone began ringing on the tray.
The screen showed the bank’s fraud department.
I answered and put the call on speaker.
A woman named Ms.
Patel