She lives alone while her own family is struggling.”
There it was.
Not remorse.
Not reconciliation.
A floor plan.
They had studied photographs of my home, counted the bedrooms, packed their belongings, and driven across Seattle believing my front gate was the only obstacle left.
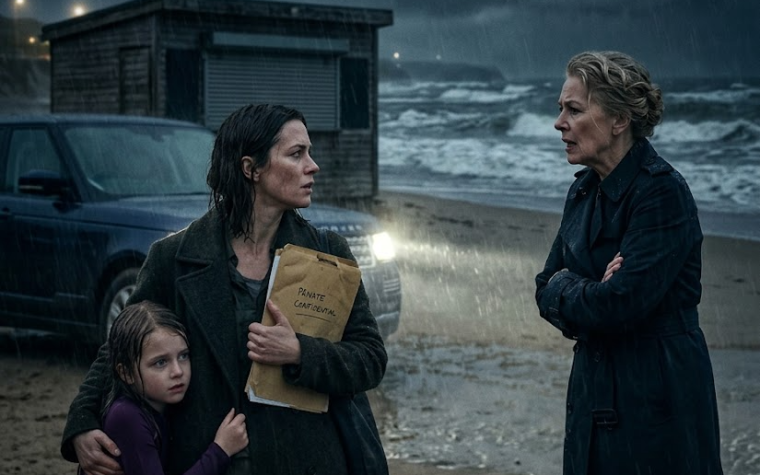
A black SUV stopped behind the U-Haul.
The driver stepped out wearing a dark raincoat and carrying a sealed envelope in a waterproof document sleeve.
He walked around the truck, checked Paige’s face against a photograph, and called her full legal name.
She backed toward the cab.
“I don’t accept anything.”
“You have been identified and served,” he said, placing the envelope on the hood.
He photographed it, recorded the time, and returned to his vehicle.
Paige stared at the envelope as though it might explode.
Christina reached for it, but Paige grabbed it first and tore it open.
Several pages slid against one another in the wind.
The first page held two signatures side by side.
One came from a refinancing application submitted six months earlier.
The other came from the credit card opened in my name thirteen years ago.
They matched.
Paige went still.
My mother leaned closer.
“What is that?”
David answered before Paige could invent anything.
“A notice preserving evidence related to an attempted fraudulent loan application.
The application listed Jasmine as a guarantor and used financial statements belonging to her company.”
Christina turned slowly toward her daughter.
“You put Jasmine’s name on our loan?”
“I was fixing it,” Paige said.
The sentence struck me with such familiarity that I had to close my eyes.
Fix it.
The same words Christina had used when Paige destroyed my credit at twenty-four.
In our family, fixing something had always meant transferring the consequences to me.
Six months earlier, my chief financial officer had received a routine verification request from a regional lender.
The request claimed that I had agreed to guarantee a cash-out refinance on Christina’s house using income from my skincare company.
The document included my legal name, an old address, my Social Security number, and a digital signature that looked convincing enough to pass a careless glance.
But the stated annual income did not match any of our filings, and the company seal was one we had retired three years earlier.
My CFO sent the application to David.
David sent it to a forensic document examiner.
The examiner found that the signature had been copied from a vendor agreement filed publicly during one of our early investment rounds.
Metadata tied the uploaded application to an email address Paige had used for her lifestyle blog.
The bank rejected the refinance and referred the file to its fraud department.
Without the new loan, the existing mortgage remained in default.
The foreclosure process resumed.
I had not caused their financial collapse.
By the time I learned about the application, they had already missed nine payments, taken two high-interest personal loans, and borrowed against nearly every asset they owned.
Christina’s designer clothes were real, but most had been purchased years earlier.
Paige’s luxury SUV was leased and three months behind.
The vacations displayed across her social media accounts had been funded by revolving credit and sponsorship advances she had already spent.
Their lives looked expensive because appearance was the final bill they always paid.
David had advised me to freeze my credit, notify the lender, preserve the evidence, and do nothing else.
Then the bank announced that the defaulted mortgage would be sold as part of a small distressed-loan portfolio.
I authorized Amnesia Holdings, a company created to purchase commercial properties for my brand, to bid on it.
David asked whether I was buying the note for revenge.
I told him no.